MWC Shanghai 2026 watch: 6G and satellite constellations enter a cost-reduction scaling phase
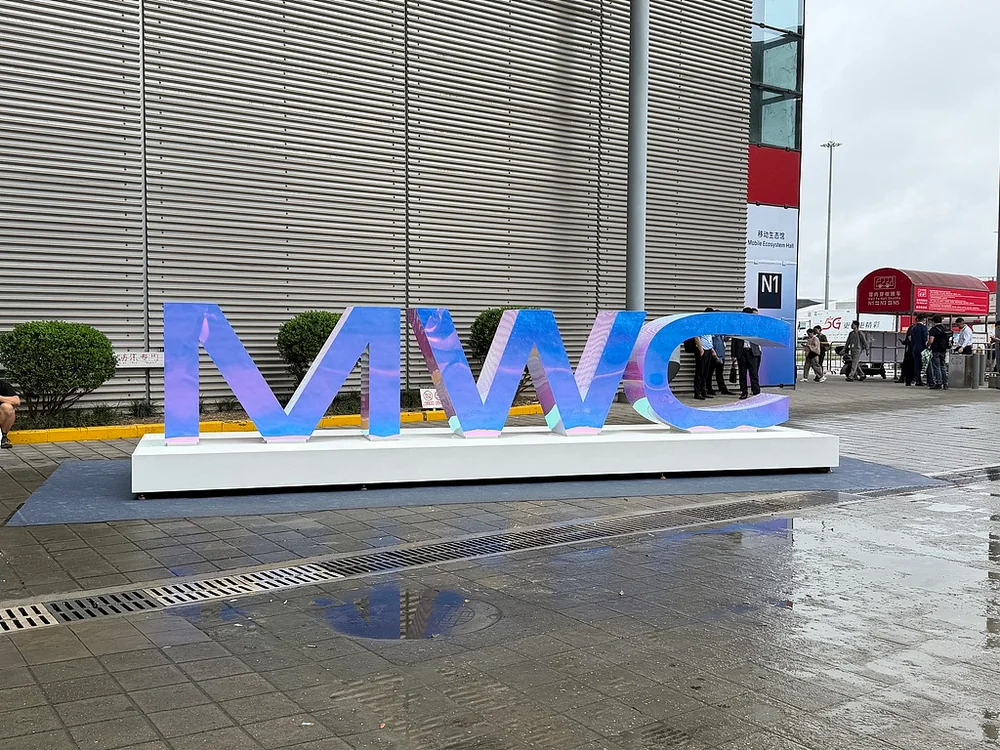
Blue Whale News, June 27 (Reporter Zhai Zhichao): MWC Shanghai 2026 opened as scheduled recently. Unlike last year's hot atmosphere of dense 5G-A commercial orders, this year's exhibition carried a more cautious and pragmatic vibe: the newly independent "6G Industrial Ecosystem Zone" and the "Future Constellation" satellite area were both packed, but the industry was more interested in figuring out when technology can turn into real money.
Blue Whale Technology found during its visit that in 6G, the three main paths—integrated sensing and communication, AI-native, and space-air-ground integration—are no longer controversial, and chip makers have already started pre-research and inventory prep. In satellite internet, the "land grab" for orbital and frequency resources is basically over; the new theme is large-scale deployment and cost reduction. But consensus stops at the technical layer: terminal makers and investors are largely waiting on the sidelines, with the former waiting for killer apps and the latter unable to calculate the payback period. Even profitable international satellite players are finding early-stage consumer-market cultivation difficult.
As the financial bill for 5G investment is not fully settled, 6G and satellite internet are collectively entering a transition period of "clear vision, hard monetization." The technical route is getting narrower, but the commercial road seems wider. Under real ROI constraints, the industry needs a more practical answer than grand narratives.
6G technical routes are converging, but the commercial loop is still being explored
Entering the 6G industrial ecosystem area in Hall N3 of MWC Shanghai, the five sections—the Beijing 6G Laboratory overall zone, communications enhancement, integrated sensing and communication, communication-compute-intelligence integration, and space-air-ground integration—make the core 6G vision clear and tangible. Staff on site told Blue Whale Technology that this is the first time in MWC Shanghai history that 6G has been given its own dedicated hall, sending a very clear industry signal: 6G has moved from concept debate to the key phase of system verification.
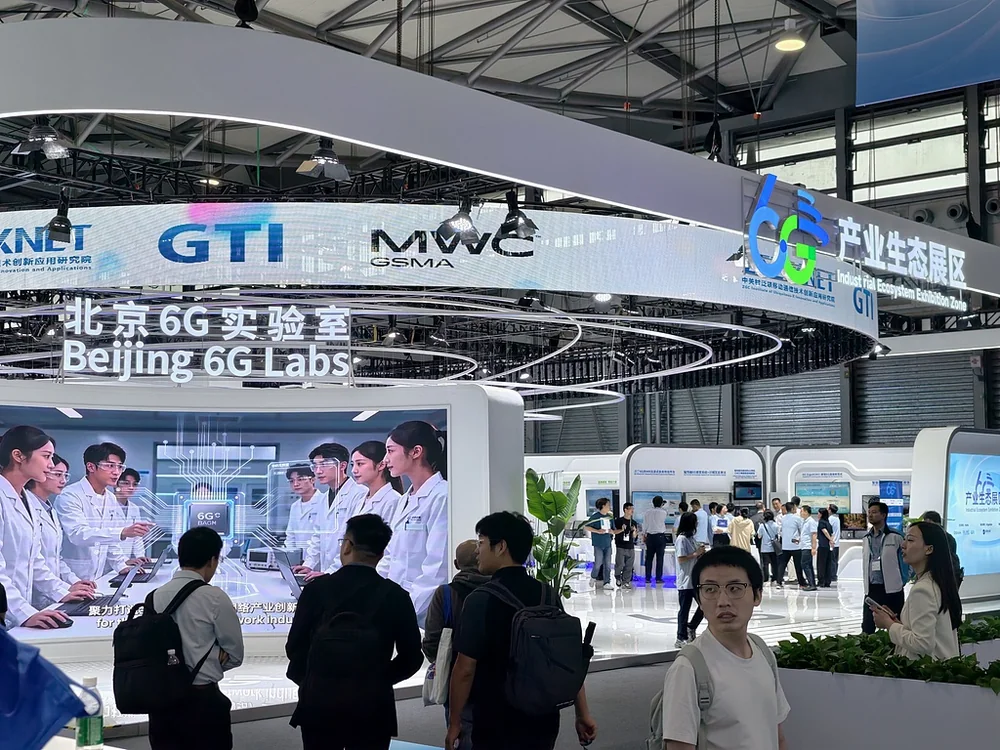
"If last year everyone was still arguing about what 6G should do, this year the argument is about how to do it and what trade-offs to make," a technical staff member in the Beijing 6G Laboratory zone told reporters. Right now, the three enhancement paths—integrated sensing and communication, AI-native, and space-air-ground integration—have basically become industry consensus, while key technologies such as terahertz communication and intelligent metasurfaces are entering prototype validation.
The upstream supply chain is speeding up noticeably. At this event, Qualcomm showed an end-to-end 6G prototype system, Galaxy Space publicly displayed its self-developed second-generation phone-to-satellite phased-array antenna for the first time in the 6G zone, and vivo showcased its 6G pre-research prototype and technical roadmap. According to reports, unlike Xiaomi, which focuses on underlying transmission algorithms, and OPPO, which focuses on communication paradigm innovation, vivo's display direction is more toward end-to-end systems and application deployment—its complete 6G test system covers the full chain, including MR terminals, 6G terminal prototypes (UE), 6G base stations (RAN), and the core network.
A representative from a domestic chip maker told reporters that the company's internal 6G pre-research team has doubled in size compared with last year, and the logic is very clear: "If we wait until the standards are frozen to start, it will be too late. We have to build the technical reserves now."
However, compared with upstream enthusiasm, terminal makers are more cautious. Blue Whale Technology asked several phone brands about their 6G terminal plans and mostly got answers like "closely monitoring." There were also few consumer-grade 6G demos at the booths. A 6G pre-research director from a top-five global smartphone maker said in an informal conversation that it is still hard to produce a clear commercial roadmap for 6G phones, not because the technology is lacking, but because the path from user needs and application scenarios to the terminal side is still being studied. In his view, 5G's experience dividend is not fully played out yet, and the immersive holographic and multi-sensory scenarios imagined for 6G are still some distance from mass consumer adoption.
Investors are equally cautious. During a break at the expo, Blue Whale Technology met an early-stage investor focused on the TMT sector. After watching several demos in the 6G zone, he said the technical evolution direction is impressive, but from an investment perspective, the capital returns of 5G are still being digested, and the R&D and network-deployment costs required for 6G are enormous. Exit cycles and return expectations still lack enough data support. He admitted that for now, the approach is to keep watching, and the right time to enter still depends on clearer commercial signals.
"Future Constellation": the pattern is set, but the path to profit still needs proof
Unlike the 6G area, which focuses on key-technology validation, the newly created "Future Constellation" satellite industry zone presents another pace of industry development—orbital competition has taken shape, and participants are now entering a phase of fine-tuning resources and costs.
Domestic low-Earth-orbit broadband and narrowband constellation operators such as Spacety, GalaxySpace, and Yinhe Satellite, along with international players like Iridium, all set up sizable booths. Spacety showcased real terminal devices for low-orbit satellite internet aimed at scenarios like ocean-going ships and desert mines. GalaxySpace highlighted Tianqi constellation use cases in IoT. Yinhe Satellite engineers even connected live and played a video-call test powered by the "Qianfan constellation."
"The fight for orbital and frequency resources in satellite internet is basically over; the key now is large-scale deployment and cost control," a representative from GalaxySpace told Blue Whale Technology. He said the mass-production cost of the company's narrowband payloads is falling steadily, but also noted that the user base for satellite internet services has not yet reached breakeven, so at least over the next few years, government and industry orders will still be the main support for revenue.
Terminal cost is another area worth watching as the business model takes shape. Blue Whale Technology spoke with antenna and module vendors about satellite communication terminal bill-of-materials costs, and most respondents said costs are falling quickly and the technology is already capable of integration into mainstream device designs, though most declined to disclose exact numbers.
An Iridium business manager said the company has already achieved positive cash flow by relying on narrowband voice and low-speed data services, but traditional market space is nearing saturation, so future growth must expand into IoT and emergency communications. Domestic low-orbit broadband constellations, meanwhile, are still in the stage of scale-first catch-up, and breakeven will require time and user accumulation.