Fed dot plot may fade: Can Warsh’s debut signal a rate hike?
The Fed’s quarterly dot plot of rate forecasts may soon lose its last cut signal — and the chart itself could even be scrapped. Markets will then reassess whether new Fed Chair Warsh (Kevin Warsh) is truly the inflation hawk he has long been portrayed as.
Warsh is now busy clarifying his stance and hearing from staff ahead of his first policy meeting later this month. On the policy path, the outside world is unlikely to get a simple answer.
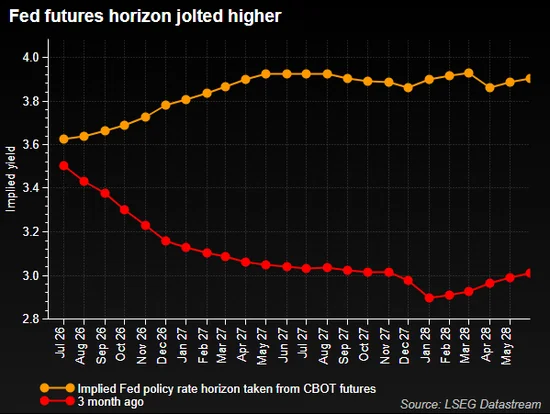
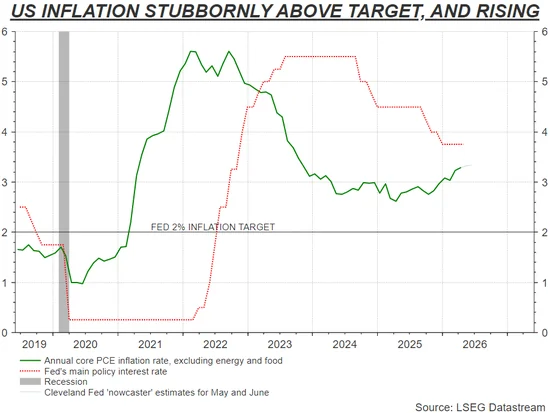
Rapid growth in artificial intelligence (AI) investment, together with a three-month surge in energy prices from the war in Iran, has pushed inflation far above target. Add divisions inside the Federal Open Market Committee (FOMC), and futures-market sentiment has turned tense, with some even betting the Fed’s next rate hike could come before year-end.
One reason doves have still had some support in recent months is the possibility of cracks in the labor market, with AI-related layoffs or output cuts at energy-related firms potentially amplifying that pressure. But there are currently few clear signs to support that view.
Instead, signs point to a labor market that remains strong and may even keep improving. A sharp rise in April job openings and May’s better-than-expected 122,000 private-sector payroll gains both point in that direction. The national nonfarm payroll report for May will be released Friday and will test that view.
The Fed will not hike rates this month, but it may be planting the seeds for future hikes.
Beyond whatever signal Warsh may send at the press conference, markets will also watch closely to see whether the Fed removes language from its prior statement suggesting a bias toward another cut. At the last rate meeting, three governors already voted to delete that wording, and at least one more recently dovish governor, Waller, has since joined them.
The real focus may be the Fed policymakers’ quarterly economic projections, especially the “dot plot” that maps out the expected path of rates over the next few years.
The current median forecast shows one more cut this year and another in 2027.
Since March, several Fed officials have signaled that expectations for cuts this year are likely to disappear from the dot plot. Whether cuts still remain in 2027 — or even flip to hikes as markets expect — could have an even bigger impact.
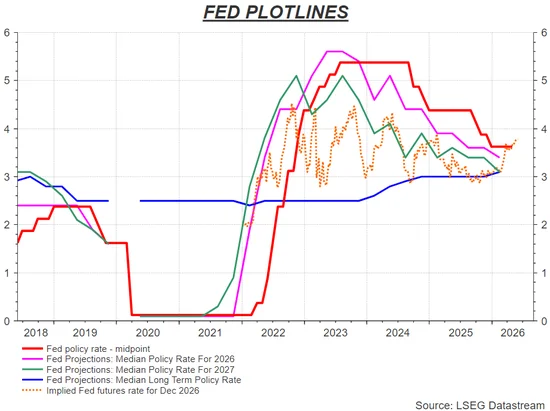
Ironically, Warsh’s dislike of so-called forward guidance may push him to abolish the dot plot altogether. That move would likely win broad support, including from his predecessor Powell, who still serves as a Fed governor.
If the Fed removes the outlook for further easing and stops offering guidance, letting markets price in future moves from new data, the rate market could become even tighter and more volatile in the second half of the year.
Of course, some investors still hope that easing will return to the agenda once the Iran war ends; others argue the hit to household demand from energy tightening is enough to restrain spending and other prices.
But more and more people now think the tide has turned.
Rate-cut plans come to a halt
SGH Macro economist Tim Duy believes the inflationary impact of higher energy prices has already outweighed the effect on growth, and that FOMC sentiment is shifting quickly as the Fed comes to realize December’s final rate cut was a mistake.
“Fed officials are realizing the risk of an inappropriate monetary policy is rising, and they are moving quickly toward a hawkish stance and paving the way for rate hikes,” he said.
“The old Warsh would have raised rates early,” he added, referring to Warsh’s long-standing reputation as a monetary hawk. “No one knows which version of Warsh will show up.”
Despite headwinds from energy, geopolitics and tariffs, the economy and stock market keep heating up as the AI investment boom accelerates, leading many to question why the Fed would even consider easing again.
Warsh’s rethinking and adjustment may differ from what markets had expected.